Showing posts with label long and foster real estate. Show all posts

Saturday, September 5, 2015

BUYERS: 5 Questions to Ask Yourself Before Getting an Appraisal

5 questions you must ask yourself before getting an appraisal

I had a reader email me a question last week asking why they should get an appraisal on their home, and I want to share with you the answer I gave them with the hope that it can help you make a similar decision. This person asked me “Why do I need to get an appraisal, I don’t want to have to pay for one”? In their particular situation a family member had died and left a home to the family. They wanted to sell it and needed to know what to ask. Some situations require you to get an appraisal such as when you buy or refinance a home, and you usually do not have a say so in the decision, however there are other times when you can make the decision yourself.
I told the person to ask themselves these 5 questions to help them.
  1. Do I have access to a recent appraisal? The owner may have had a recent appraisal done on the home that could be used, such as with a refinance or a recent purchase. A recent appraisal can give you a good estimate of value if the real estate market hasn’t changed much since it was done, and if this is the case I wouldn’t recommend getting a new one.
  2. Can I get information on home sales in my neighborhood, and if so are the homes very similar to my house? Some neighborhoods are what we call cookie cutters, meaning that they are all very similar in age, style, size, and appeal. If this is the case, and there have been recent sales and some current listings, then you may be able to estimate the value on you own. You can read more about doing this on a past post I wrote.
  3. If I get an appraisal will the cost be offset by the money saved? I recently did an appraisal on a home a person was buying. They were not getting a loan from a bank so they did not have to get the appraisal, however they wanted to know if they were paying the right price. The appraisal value came in approximately $15,000 lower than the contract amount! The cost of an appraisal varies across the country, but in the Birmingham, Alabama area the average is about $350-$450 for a typical house. Would you pay this to save $15,000?
  4. If I don’t get an appraisal will it prevent me from selling my home in a reasonable amount of time? This is related to #3 because it compares the additional cost you may have to pay if you don’t get an appraisal. By asking yourself this question you take into consideration the cost of holding on to the house for an extended period of time. If you price your home too high, and it takes 4 months longer to sell than if you had priced it more competitively with the market, then this additional cost must be weighed against the cost of the appraisal. If your mortgage payment is $1,000 then this additional cost would be $4,000, which would be about 10 times the cost of the  appraisal we discussed previously. You need to determine if this is a good return on your investment.
  5. Am I committed to actually using the appraisal? Some people get an appraisal but will not use the value estimate to set a list price because they don’t like the value. Sounds crazy, huh? Why pay for an appraisal if you’re not going to use it? People allow their emotions to take over and ignore the value arrived at by a professional and unbiased appraiser. The appraiser is trained to be unbiased and provide a report that reflects the local market. If used correctly the appraisal will help you price your home to the market so it sells in a reasonable amount of time for the what the market will support.
If you have read through these five questions and decided that an appraisal can help you sell your home, please give me a call. I can answer any other questions you may have-no strings attached. I am committed to helping homeowners sell their home by pricing it properly and look forward to speaking with you.


Read more http://birminghamappraisalblog.com/appraisal/5-questions-you-must-ask-yourself-before-getting-an-appraisal/

Friday, August 14, 2015

Move This, Not That: 10 Items to Get Rid of Before Your Next Move

Donate
When it comes to moving, deciding what to take with you — and what to leave behind — can be stressful. Spending a little time clearing out dead weight before the move will make settling into your new place much more freeing. Check these 10 areas of your home for items that aren’t worth the square footage in the moving van — or your new home.

1. Dine in

This may seem obvious, but food takes up a lot of space and often gets a bit lost in the moving shuffle. In the weeks before your move, eat anything that isn’t shelf-stable, brand-new or a specialty item. Don’t forget about the perishable foods in the fridge and freezer (steak for dinner, anyone?). Take a break and throw a pantry dinner party with friends who are helping you move.

2. Pass on low-quality furniture

Low-quality furniture, typically made of particle board, is very susceptible to being ripped and chipped in a move. Ask family and friends if they can use any of these pieces or bring them to your local donation center. Upgrade or replace when you get to your new home.

3. Clean closets

Anything old, stained or that no longer fits should go straight into the donation bin. Moving cross-country? Transitioning from a cold climate to Florida will allow you to shed even more weight as you let go of snowsuits and boots that won’t be of use in the Everglades. Donate to a local thrift store or have a garage sale to make extra cash.

4. Tame the bathroom cabinet

There is no sense moving 20 crusty nail polishes and every curling mousse you’ve ever tried and abandoned. Anything expired or unused lately should be tossed. Cull these and only keep your essentials, as anything else may spill in transit and many are flammable.

5. Make a pitcher of margaritas

While you’re throwing your pantry party, be sure to bring out the open bottles of alcohol. Chances are they’re in glass, making them a no-no for most moves, so you might as well enjoy them now.

6. Burn those candles

This may sound odd, but many moving companies won’t take candles. They’ll most likely melt and get misshapen anyway, so give these to friends or use them as décor at your clean-out party.

7. Donate excess kids’ toys

Toys take up a massive amount of space, even if they are lightweight. Anything that has been outgrown or unused should be donated or passed along to friends or family. Bigger items such as outdoor pools, sports equipment and bicycles should also be assessed.

8. Toss old linens

Sheets and towels are bulky to move, so anything that’s seen better days should be put in the donate pile. Choosing fresh sheets and towels after you’ve moved is a fun part of feeling settled in your new home.

9. Clear out garage clutter

This includes outdoor furniture, hoses, planters and trash cans. With garden items, it’s best to start new instead of moving a potentially invasive weed or insect species to a new area. Outdoor furniture often has glass, which is easily shattered, and flimsy outdoor fabric, which is easily torn in a move. Try selling these pieces and using the cash for a new set.

10. Hobby supplies

Excessive amounts of craft or hobby supplies are often not worth the space. Use this as a time to freshen things up and pare down your supply stash. Bonus? An excuse to buy new supplies in the future.
Once you’ve tamed these 10 areas, you should be able to breathe a little easier and pack a little lighter. You’ll be left with high-quality furniture, sentimental pieces and daily-use items, all things that help make a house a home.

Monday, August 10, 2015

Need a New Car? Consider a Car Buying Service. Better Ways To Reach The Beach

Thinking About Using a Car-Buying Service? 6 Things to Know First
It is possible to save money (and agitation) on a new ride without ever speaking to a car dealer yourself. Here’s how it works.
By Michael Koretzky on August 10, 2015 / Photo (cc) by pedrosimoes7
Buying a Car: How Can a Dealer Sell a Car Below Invoice? featured image large thumb0
Reach the Beach in Ocean City MD –    Beach Properties  Long & Foster
The last two new cars I bought, I did so without speaking to a salesman.
I bought a vehicle in 2004 after emailing every dealer within a 50 mile radius of my house. I haggled via email with a half-dozen of them, probably spending about the same amount of time it would have taken to visit a couple of showrooms.
My car before that, a brand-new 1996 Oldsmobile, was an easier experience. I simply hired a car broker I learned about from a co-worker. The broker called me, asked what I was looking for, discussed prices and options, and went on his merry way. A week later, he found the perfect car at a near-perfect price. He even had it delivered to the parking lot at my office building.
Best I can tell, I saved a couple thousand dollars by buying a car online, and slightly less buying a car through a broker. These are two of the options to consider if you want to buy a car. Here’s a guide to these and related ways to make this important purchase, and other key considerations before you take the leap.
  1. Not all services are the same
As you saw in the video above, Money Talks News founder Stacy Johnson recently used a car buying concierge service, Authority Auto, that saved him $2,000, but he spent $795 to do it, so he only netted $1,205. Still, spending $795 to make $2,000 is a 60 percent return on investment within a very short time — good by pretty much any standard.
In my case, the broker I hired didn’t cost me a dime. He made his money by charging the dealer instead of charging the customer. Brokers often have close relationships with a handful of dealers in the area who are willing to give them a discounted price because of the volume of sales they generate.
I could have gone to a car concierge like the one Stacy used. They generally charge customers a flat fee or a percentage of the savings they generate for the buyer. Generally, a concierge scores deals by casting a wider net. As the name implies, concierges excel at buying luxury or harder-to-find vehicles.
In addition, there are car-buying services available through membership organizations, such as the AAA Auto Buying Service and the Costco Auto Program. (AAA is regional or sometimes just by state, so it’s best to just track down the link on your local club’s website. Go towww.aaa.com to get started.) Many credit unions also offer this service, like this one from PenFed, or this one from USAA.
Before selecting a service, get the answers to these questions:
  • How is the service paid? If the service is being paid by the dealership, what gives it the incentive to find you the best possible price?
  • What services are included? Will the contract be ready for your signature? Will the car be delivered to you? Is the service simply introducing you to potential sellers? What else is involved?
  1. Consider selling your old car on your own
In my case, the car broker offered to include my old car in the deal for a new one. But I quickly figured out I could sell my ancient, no-frills Nissan hatchback on my own for a few hundred more.
Then I had a change of heart and let the broker handle the trade-in. Why? Because I was willing to lose some value if I could gain some free time.
Do this math for yourself. If you’re willing to put in the hours, sell your trade-in and pocket the cash. If it’s too much hassle, or if you live in a small town where your customer base may be limited, consider doing what I did.
  1. Do your own research
A broker, concierge or buying service can save you legwork, but you still need to do your homework. Spend some time online studying what vehicle you want, the options you crave and those you could do without. You want to give the service as much detail as possible. In my case, the broker said I would save time and money if I didn’t care what color my Oldsmobile was. So I ended up with a red car, which was fine with me.
  1. Line up your financing in advance
There’s no point in shopping for a car, or anything else, until you know you have the money to buy it. Shopping for a car before securing the loan is like stepping on the gas before you’re in gear: You may make a lot of noise, but you’re not going anywhere.
  1. Figure out what happens afterward
What happens if you get a lemon? What if you just don’t like the car when you show up on the lot or it’s delivered to your door? Also, if you want it to be maintained by a dealership, where’s the nearest one that services your make? Besides the potential savings, a major advantage to embracing one of these services is sparing you time and hassle. If you don’t ask these questions upfront, you could be facing complications and demands on your time after the sale.
  1. Consider what your time is worth
If I had to do it all over again, would I use another broker or buy on my own? At the time I called the broker, I was starting a new job, so it was invaluable to me to have someone else handle the purchase — even worth forgoing a few hundred dollars on the sale of my old car — so I could focus on proving my value at work. And I ended up getting a great deal on the car.
However, shopping and comparing prices online continues to become more efficient, so hunting down the best deals on a new car and selling an old car becomes an increasingly worthwhile DIY project. If you’re willing to put in the time online, you can save more, especially if you’re buying a popular, midpriced model that many dealers have stacked on their lots.

Wednesday, August 5, 2015

Money Saving Maintenance Tips for Rental Properties

By Silvia Englert, General Manager at Houserie.com
RISMEDIA, Wednesday, August 05, 2015— One of your responsibilities as a landlord is to take care of maintenance and repair issues in your rental. Regular maintenance can help you catch small problems before they turn into big expansive problems and will in the long run save you lots of money, time and reduce the number of tenant complaints!


Image result for rental home photo       

Buying A Home VS Renting: Weigh All the Factors   consider options when looking at beach resort real estate.  Ask Long & Foster Real Estate - Ocean City for advice on the local market.   Visit:   http://www.susanantigone.com/


Here are some maintenance tips that can save you money:

1. Test all smoke and carbon monoxide detectors regularly. 
Set a regular schedule to test all detectors. Also be aware that the average lifespan of a carbon monoxide detector is five years, and of most smoke alarms 10 years. Replace according to manufacturer recommendations. These devices save lives and can help minimizing damage by alerting people when there is a fire! Be aware that if these devices are not in working order, you can face legal action. 

2. Have a thorough electrical inspection done by a qualified technician at least once every 10 years.
This inspection will reveal any problems with unsafe wiring and circuits that could cause an electrical fire. In addition, if your rental unit comes with appliances, make sure that these are in good working order before new tenants move into the property.

3. Check for water damage and leaks.
Check for leaks and soft spots after heavy rain storms. Also look for signs of water around windows, showers, and toilets and check under sinks, boilers, and water heaters. Identifying water leaks early can prevent major damage to walls, ceilings, and a tenant’s possessions. It also prevents dangerous mold!

4. Inspect shower caulking and grout between tiles.
Wear and tear on bathroom and kitchen surfaces can result in mold and even cracking of tiles. Prevent any moisture or mold from getting below the surface by making sure the areas around tiles, tubs and sinks are sealed.

5. Inspect and treat for pests on a regular basis.
Even if you do not currently have a pest problem, you should exterminate on a regular basis to prevent such problems from occurring. Tenants hate seeing bugs in their home and keeping up with pest control will prevent a larger pest problem later on. In addition, regular termite inspections should be performed as well. Pest control is usually best left to a professional.

6. Inspect heating and air conditioning systems regularly and replace air filters more often.
Heating or air-conditioning systems should be inspected at least once a year. This will help to ensure that such systems are able to run safely, as well as efficiently. Filters should be replaced regularly at least a couple of times a year. A simple $15 filter for a furnace or air conditioner can potentially save a landlord thousands of dollars in repairs. Dirty filters can increase your utility bill by causing the system to work harder or can lead to malfunctions in the systems. Replacing the filter will help prevent the air duct from becoming contaminated. If clogged, the ducts will need to be professionally cleaned, and that is an expense you do not want to incur.

7. Paint your property before damage occurs.
Painting inside and out does not only make your property look better but it can actually help to prevent water damage, mold and rot. If you have noticed that the paint on your property has started to peel, paint immediately!

8. Flush your water heater.
Once or twice a year, you should drain and flush your property’s water heater. This needs to be done to remove the sediment that can build up in your unit which can reduce the efficiency of your water heater and clog the drain valve. Replacing a water heater is expensive! 

By spending a little time and money now to perform property maintenance, you can save yourself a lot of time and money in the future. Another way to save money in the long run as a landlord is to perform a comprehensive tenant background screening on every prospective tenant.

For more Information, please visit www.houserie.com, follow and like us onFacebook or visit our Landlord Blogs.
RISMedia welcomes your questions and co

Tuesday, August 4, 2015

Selling Your Home? Price It Right From the Start!

Selling Your Home? Price It Right From the Start!


In today’s market, where demand is outpacing supply in many regions of the country, pricing a house is one of the biggest challenges real estate professionals face. Sellers often want to price their home higher than recommended, and many agents go along with the idea to keep their clients happy. However, the best agents realize that telling the homeowner the truth is more important than getting the seller to like them.
There is no “later.”
Sellers sometimes think, “If the home doesn’t sell for this price, I can always lower it later.” However, research proves that homes that experience a listing price reduction sit on the market longer, ultimately selling for less than similar homes.
John Knight, recipient of the University Distinguished Faculty Award from the Eberhardt School of Business at the University of the Pacific, actually did research on the cost (in both time and money) to a seller who priced high at the beginning and then lowered the their price. In his article, Listing Price, Time on Market and Ultimate Selling Price published in Real Estate Economics revealed:
“Homes that underwent a price revision sold for less, and the greater the revision, the lower the selling price. Also, the longer the home remains on the market, the lower its ultimate selling price.”
Additionally, the “I’ll lower the price later” approach can paint a negative image in buyers’ minds. Each time a price reduction occurs, buyers can naturally think, “Something must be wrong with that house.” Then when a buyer does make an offer, they low-ball the price because they see the seller as “highly motivated.” Pricing it right from the start eliminates these challenges.
Don’t build “negotiation room” into the price.
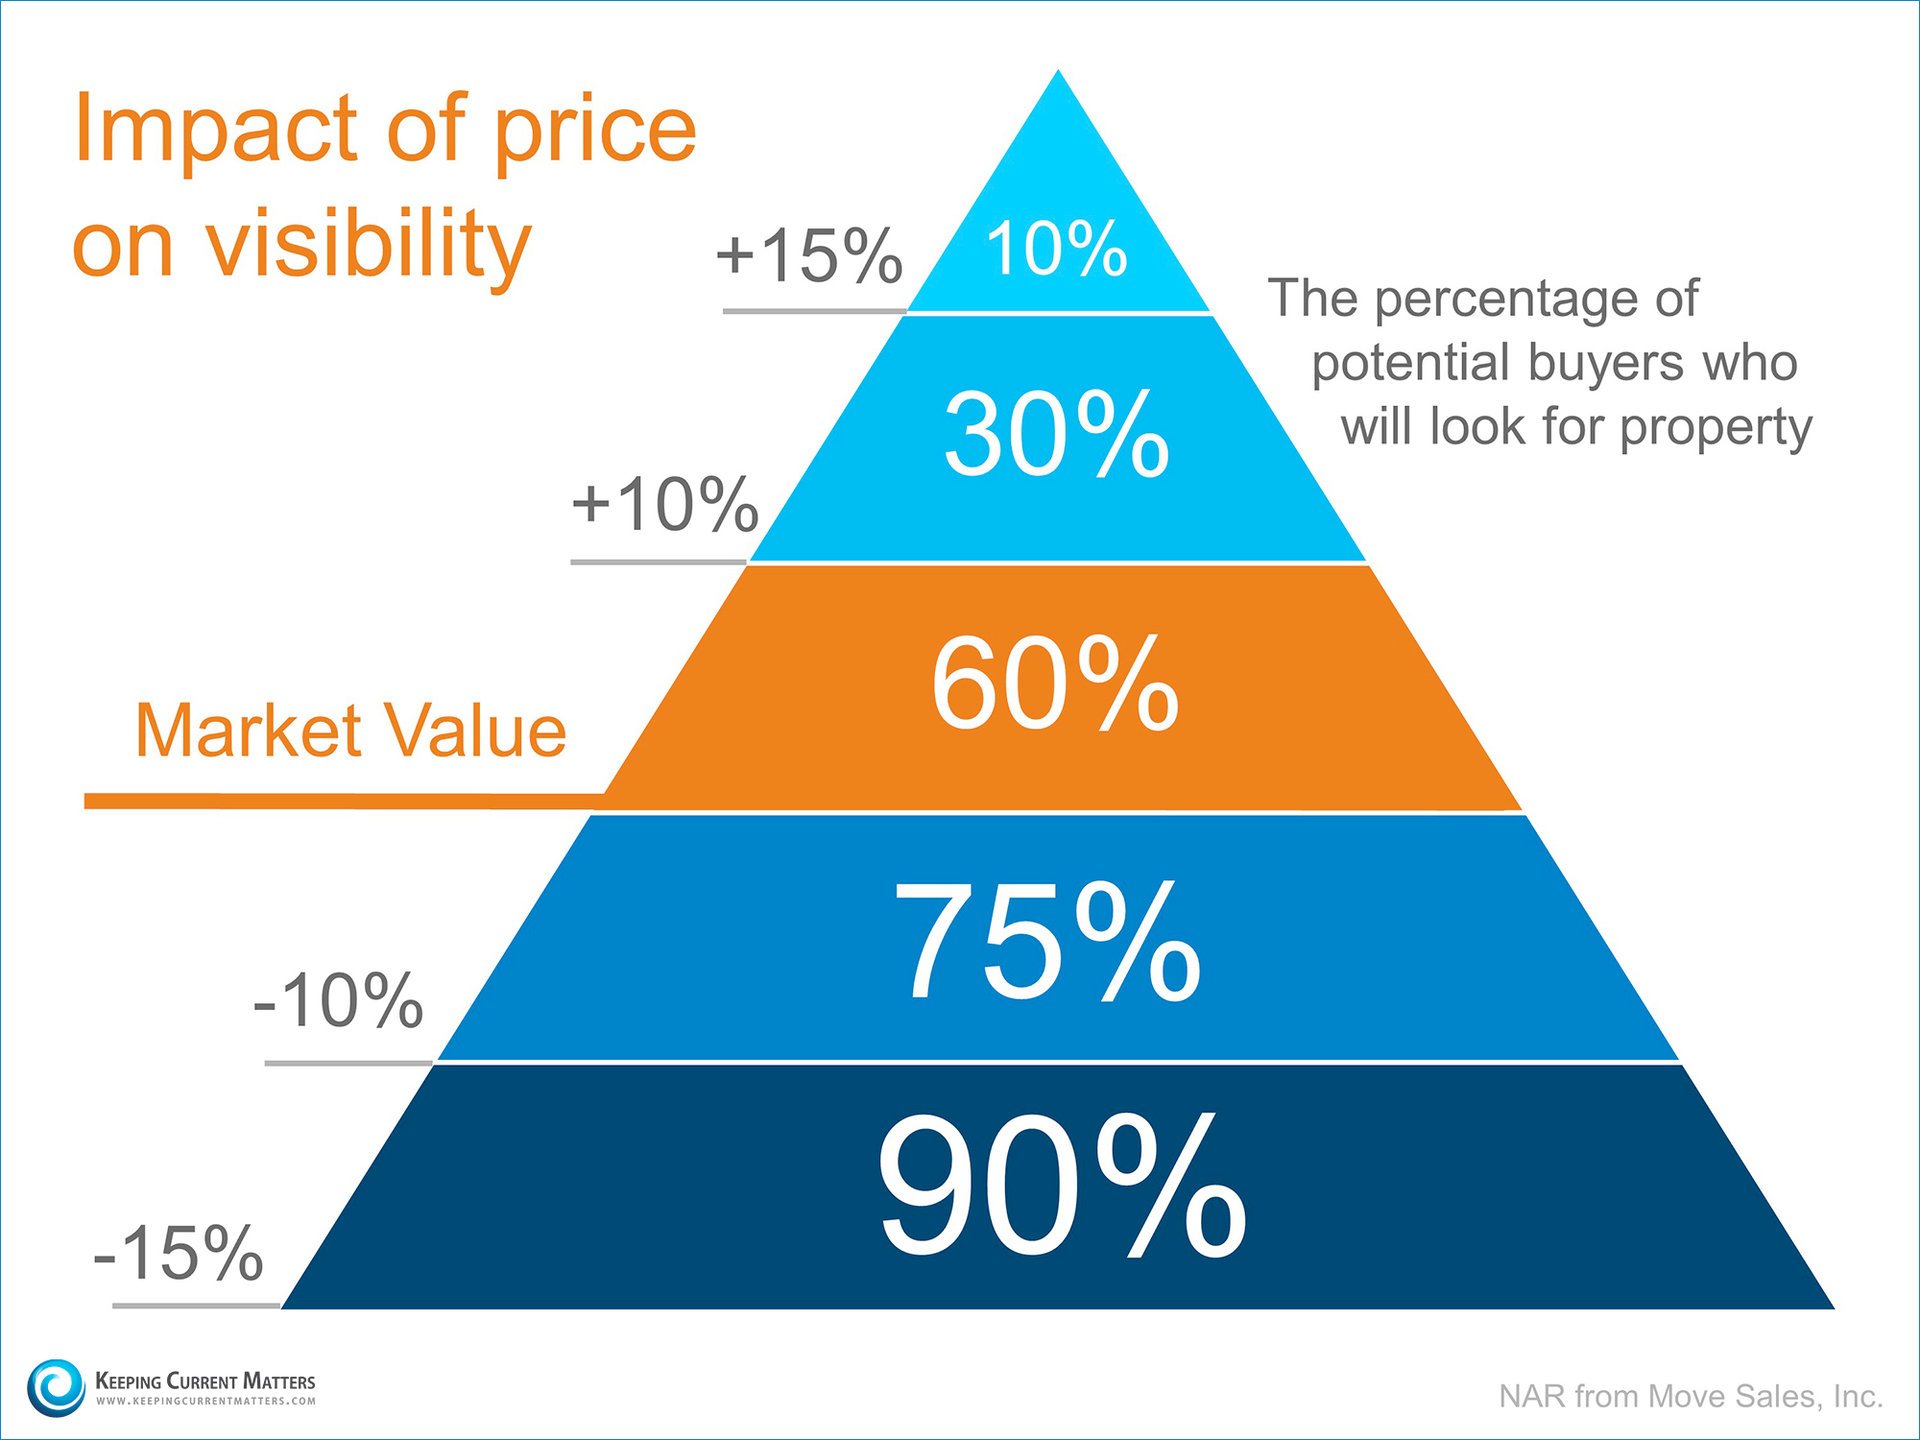
Many sellers say that they want to price their home high in order to have “negotiation room.” But, what this actually does is lower the number of potential buyers that see the house. And we know that limiting demand like this will negatively impact the sales price of the house.
Not sure about this? Think of it this way: when a buyer is looking for a home online (as they are doing more and more often), they put in their desired price range. If your seller is looking to sell their house for $400,000, but lists it at $425,000 to build in “negotiation room,” any potential buyers that search in the $350k-$400k range won’t even know your listing is available, let alone come see it!
One great way to see this is with the chart below. The higher you price your home over its market value, the less potential buyers will actually see your home when searching.
Price & Visibility | Keeping Current Matters
A better strategy would be to price it properly from the beginning and bring in multiple offers. This forces these buyers to compete against each other for the “right” to purchase your house.
Look at it this way: if you only receive one offer, you are set up in an adversarial position against the prospective buyer. If, however, you have multiple offers, you have two or more buyers fighting to please you. Which will result in a better selling situation?
The Price is Right
Great pricing comes down to truly understanding the real estate dynamics in your neighborhood. Look for an agent that will take the time to simply and effectively explain what is happening in the housing market and how it applies to your home.
You need an agent that will tell you what you need to know rather than what you want to hear. This will put you in the best possible position
.

Thursday, July 16, 2015

Summer Vacation Time? 8 Tips for a Financially Sane Vacation

8 Tips for a Financially Sane Vacation

By  on 
Have you taken your summer vacation yet? Or has your vacation taken you?
Some people travel on autopilot. You cart the kids off to Disneyland because you’re supposed to? Or, you fly to Europe because everyone says you should see Paris before you die.
But what do you want?
“Most of us don’t take the time to think about what would make us happier — what kind of vacation would be relaxing, would recharge our batteries, would be a great time with family,” says Donna Skeels Cygan, a Certified Financial Planner and author of “The Joy of Financial Security.”
Cygan suggests having a “values talk” with your spouse and/or family before planning a vacation. Clarify what everyone expects: Adventure? Relaxation? Roller coasters?
The same holds true for singles. Ask yourself what kind of vacation fits your personality instead of listening to everyone else’s preferences.
The trip you want could be well within reach. Whether it’s a staycation or atrip to Sicily, use these tips to cut costs.

1. Book smart when flying or renting a car

Airplane 14686405763_b0ed171660_k
There is no need to pay full freight when you fly, thanks to websites likeTripAdvisor, Expedia and CheapOair.
You also can learn more about cutting flight costs by reading “12 Ways to Land Cheaper Airfare.”
Plan to rent a car? Use discount travel websites, and check your auto insurance to see if you can decline additional coverage on the rental car.
If you need a vehicle for just a day or two and the quoted rate is exorbitant, rent a pickup from U-Haul for $19.95 a day.
A car-sharing service like CityCarShare will let you rent for only a few hours. Some rental agencies, including Enterprise and Hertz, also have gotten into the sharing business.
For more tips on getting around, see “On Your Dream Trip? You Don’t Need a Rental Car.”

Sunday, July 5, 2015

Summer Beach Vacation Home: 5 Things to Know Before Renting Out Your Home

men sitting and talking at a table
A credit check can offer insights into your applicant’s payment history and gives you a good idea if they’ll likely be a good or bad credit risk.

Owning a rental property requires hard work, patience, and planning.

Ocean City MD real estate.  Renting or owning a vacation home. 

If you’ve entertained thoughts about renting out your home, you may be asking yourself a few questions: “Is it worth hanging on to this property?” “How will I feel about strangers moving into my home?” “Will my tenants be responsible?”
Owning a rental property can require hard work, patience, and planning. There’s the good to consider, like the potential to increase your income and build a steady cash flow. On the other hand, being a landlord may test your ability to deal with the unexpected, like emergency home repairs or unreliable renters.
Before you hand over the keys, here’s what you can do to make the rental process go smoother.
1. Research the market
Research the market in the neighborhood of your rental home to choose a rent amount that matches local rates while still helping you earn a profit. Consider the square footage and number of bedrooms and bathrooms.
You might also take into consideration any additions to the property and the age of the home. Don’t forget to factor in costs like pest control, lawn maintenance, andoccasional home repairs.
2. Grace your home with curb appeal
The first impression of your home’s curb appeal can mean everything, and depending on where you live and the time of year, your home may have taken a beating from the sun, wind, rain, or snow.
To give your home a fresh look, rent a power washer, clean out the flower beds, and trim shrubs and low-hanging tree branches. Give your lawn a clean trim, your panels a new coat of paint, and your shutters a good cleaning.
3. Check to see if your prospective tenant is financially responsible 
A credit check can offer insights into your applicant’s payment history and gives you a good idea if they’ll likely be a good or bad credit risk.
You may also want to consider hiring a reputable company that can perform a tenant screening on your potential occupants to find out if they’ve damaged previous rental properties or have a criminal record. You can also ask for referrals from past residences since this information won’t be included in a credit report.
4. Plan for financial emergencies
Renting comes with its own set of unexpected emergencies, from tenants suddenly vacating a property to their calling you on a Sunday about a broken water heater. These can be tough expenses to bear, and as a landlord, it will behoove you to set aside funds for such situations.
5. Get appropriate insurance coverage
There’s always the possibility that your tenants or one of their guests might have an accident or damage your property. You could also experience a loss of rental income due to an unforeseeable disaster. The proper insurance may cover these things along with legal fees if you end up taking your tenant to court.
For some, becoming a landlord is all about on-the-job training. It can be a challenge, but in the end, renting out your extra space can help you reap financial benefits.
- See more at: http://www.trulia.com/blog/5-things-to-know-before-you-rent-out-your-home/#sthash.kjis2DGg.dpuf